
Isobutane Price Surge and Supply Shocks: A Market in Flux
Here is a number that has caught the attention of everyone in the NGL and petrochemical markets: 145 cents per gallon. That was the price of isobutane in Mont Belvieu last week, its highest level in four years. What is even more striking is the differential. Isobutane is now trading more than 40 cents per gallon above normal butane, a blowout that has only happened once before since 2024 . The two C₄ isomers share the same chemical formula but serve completely different markets. Normal butane is typically used as a cheap gasoline blending component. Isobutane, on the other hand, is the refinery’s go-to feedstock for alkylation to produce high-octane alkylate. It also finds its way into aerosol propellants and refrigerants.
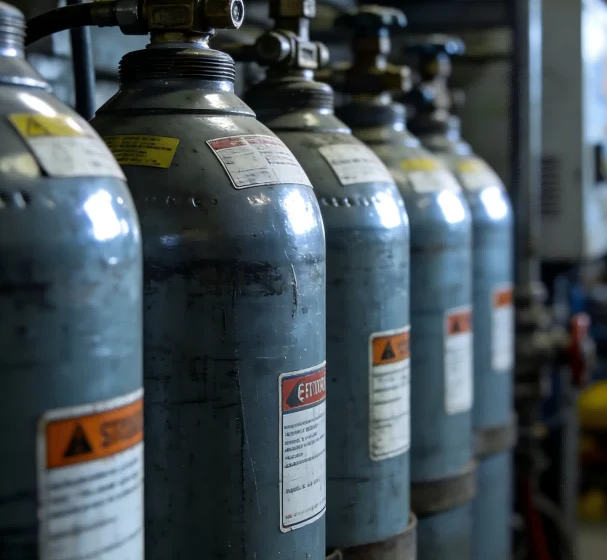
So, what is behind this sudden spike? The isobutane market is notoriously thin, dominated by a few major players, which makes it susceptible to sharp price movements. In the past, abnormal differentials were usually blamed on butamer units being offline or a surge in octane value. This time, the octane argument is certainly in play, but a new and unusual factor has emerged: petrochemical crackers are reportedly buying up isobutane. According to OPIS, at least two petrochemical operators are using it as cracking feedstock, which is a highly unusual demand source for isobutane in the U.S. market.
This price volatility is not an isolated event. The first half of 2026 has already been a rollercoaster for the market. After a weak start to the year, prices were jolted in March by geopolitical tensions. The disruption in the Strait of Hormuz and a spike in crude oil prices sent shockwaves through commodity markets, pushing domestic isobutane prices to a 2026 high of 7,100 yuan per ton on March 23. While prices retreated from that peak, the geopolitical backdrop remains the single biggest wildcard for the rest of the year. Analysts suggest that if tensions ease, prices could drift lower into a 5,000-6,500 yuan range. However, any escalation could reignite the rally.
Adding to the supply-side drama, the market in Asia is currently dealing with a significant tightening of domestic supplies. As of late June, the shutdown of Shenghong Refinery, which had been a major supplier, created a daily supply gap of 2,000-2,300 tons. This domestic reduction is being felt across the region, and it is happening at the same time as the market navigates the impact of new sanctions. Since January 26, 2026, new sanctions regulations have covered isobutane, closing a previous loophole that had allowed imports from Russia. This has forced companies to scramble for alternative supply sources.
The scramble for new supply was illustrated by a notable logistical feat in February. Polish fuels group Unimot completed its first direct delivery of isobutane from the United States for a long-term client. This shipment was not just a simple purchase; it represented a major strategic shift. Unimot used a leased terminal in Wilhelmshaven, Germany, and rail transport provided by its subsidiary to move the product. The company had prepared for this scenario back in May 2024, securing the terminal infrastructure ahead of the sanctions’ implementation.
“We are pleased that this loophole has been closed—it is an important step toward greater predictability and security of supply chains,” said Grażyna Pawlak, Vice President of the Management Board for Trading at Unimot Paliwa. “At the same time, our first delivery from the United States shows that it is becoming a strategic sourcing direction for us for this product. Thanks to earlier preparations, including leasing the terminal in Wilhelmshaven, we are able to respond flexibly and deliver comprehensive supplies to our customers, even in a demanding market environment,” she added.
While the short-term market news is dominated by price spikes and sanctions, the long-term trajectory of the isobutane market appears to be one of steady growth. The global isobutane market is projected to grow from USD 21.15 billion in 2025 to USD 22.23 billion in 2026, eventually reaching USD 33.71 billion by 2034. The Asia-Pacific region holds the largest share, driven by immense demand from China, India, and Japan . While its flammability and strict safety regulations remain a challenge—especially in consumer applications like refrigerants and aerosols—the push for eco-friendly solutions is opening new doors. Bio-based isobutane, produced from renewable feedstocks, is gaining traction as industries look to align with green chemistry and carbon neutrality goals .The picture that emerges is one of a complex market trying to balance competing forces. On one side, geopolitical instability and sanctions are rerouting global supply chains, creating immediate price shocks. On the other, the fundamentals of the chemical industry and the shift towards sustainability point toward a long-term demand increase. For now, the industry is focused on the immediate: finding alternative supplies, managing volatile costs, and watching for the next big market move.